The Scenario
An experienced investor identified an auction property requiring renovation. The investment
strategy was: acquire quickly via auction, renovate, and refinance into a buy-to-let mortgage.
This case study breaks down the actual numbers.
Property Details
- Auction hammer price: £185,000
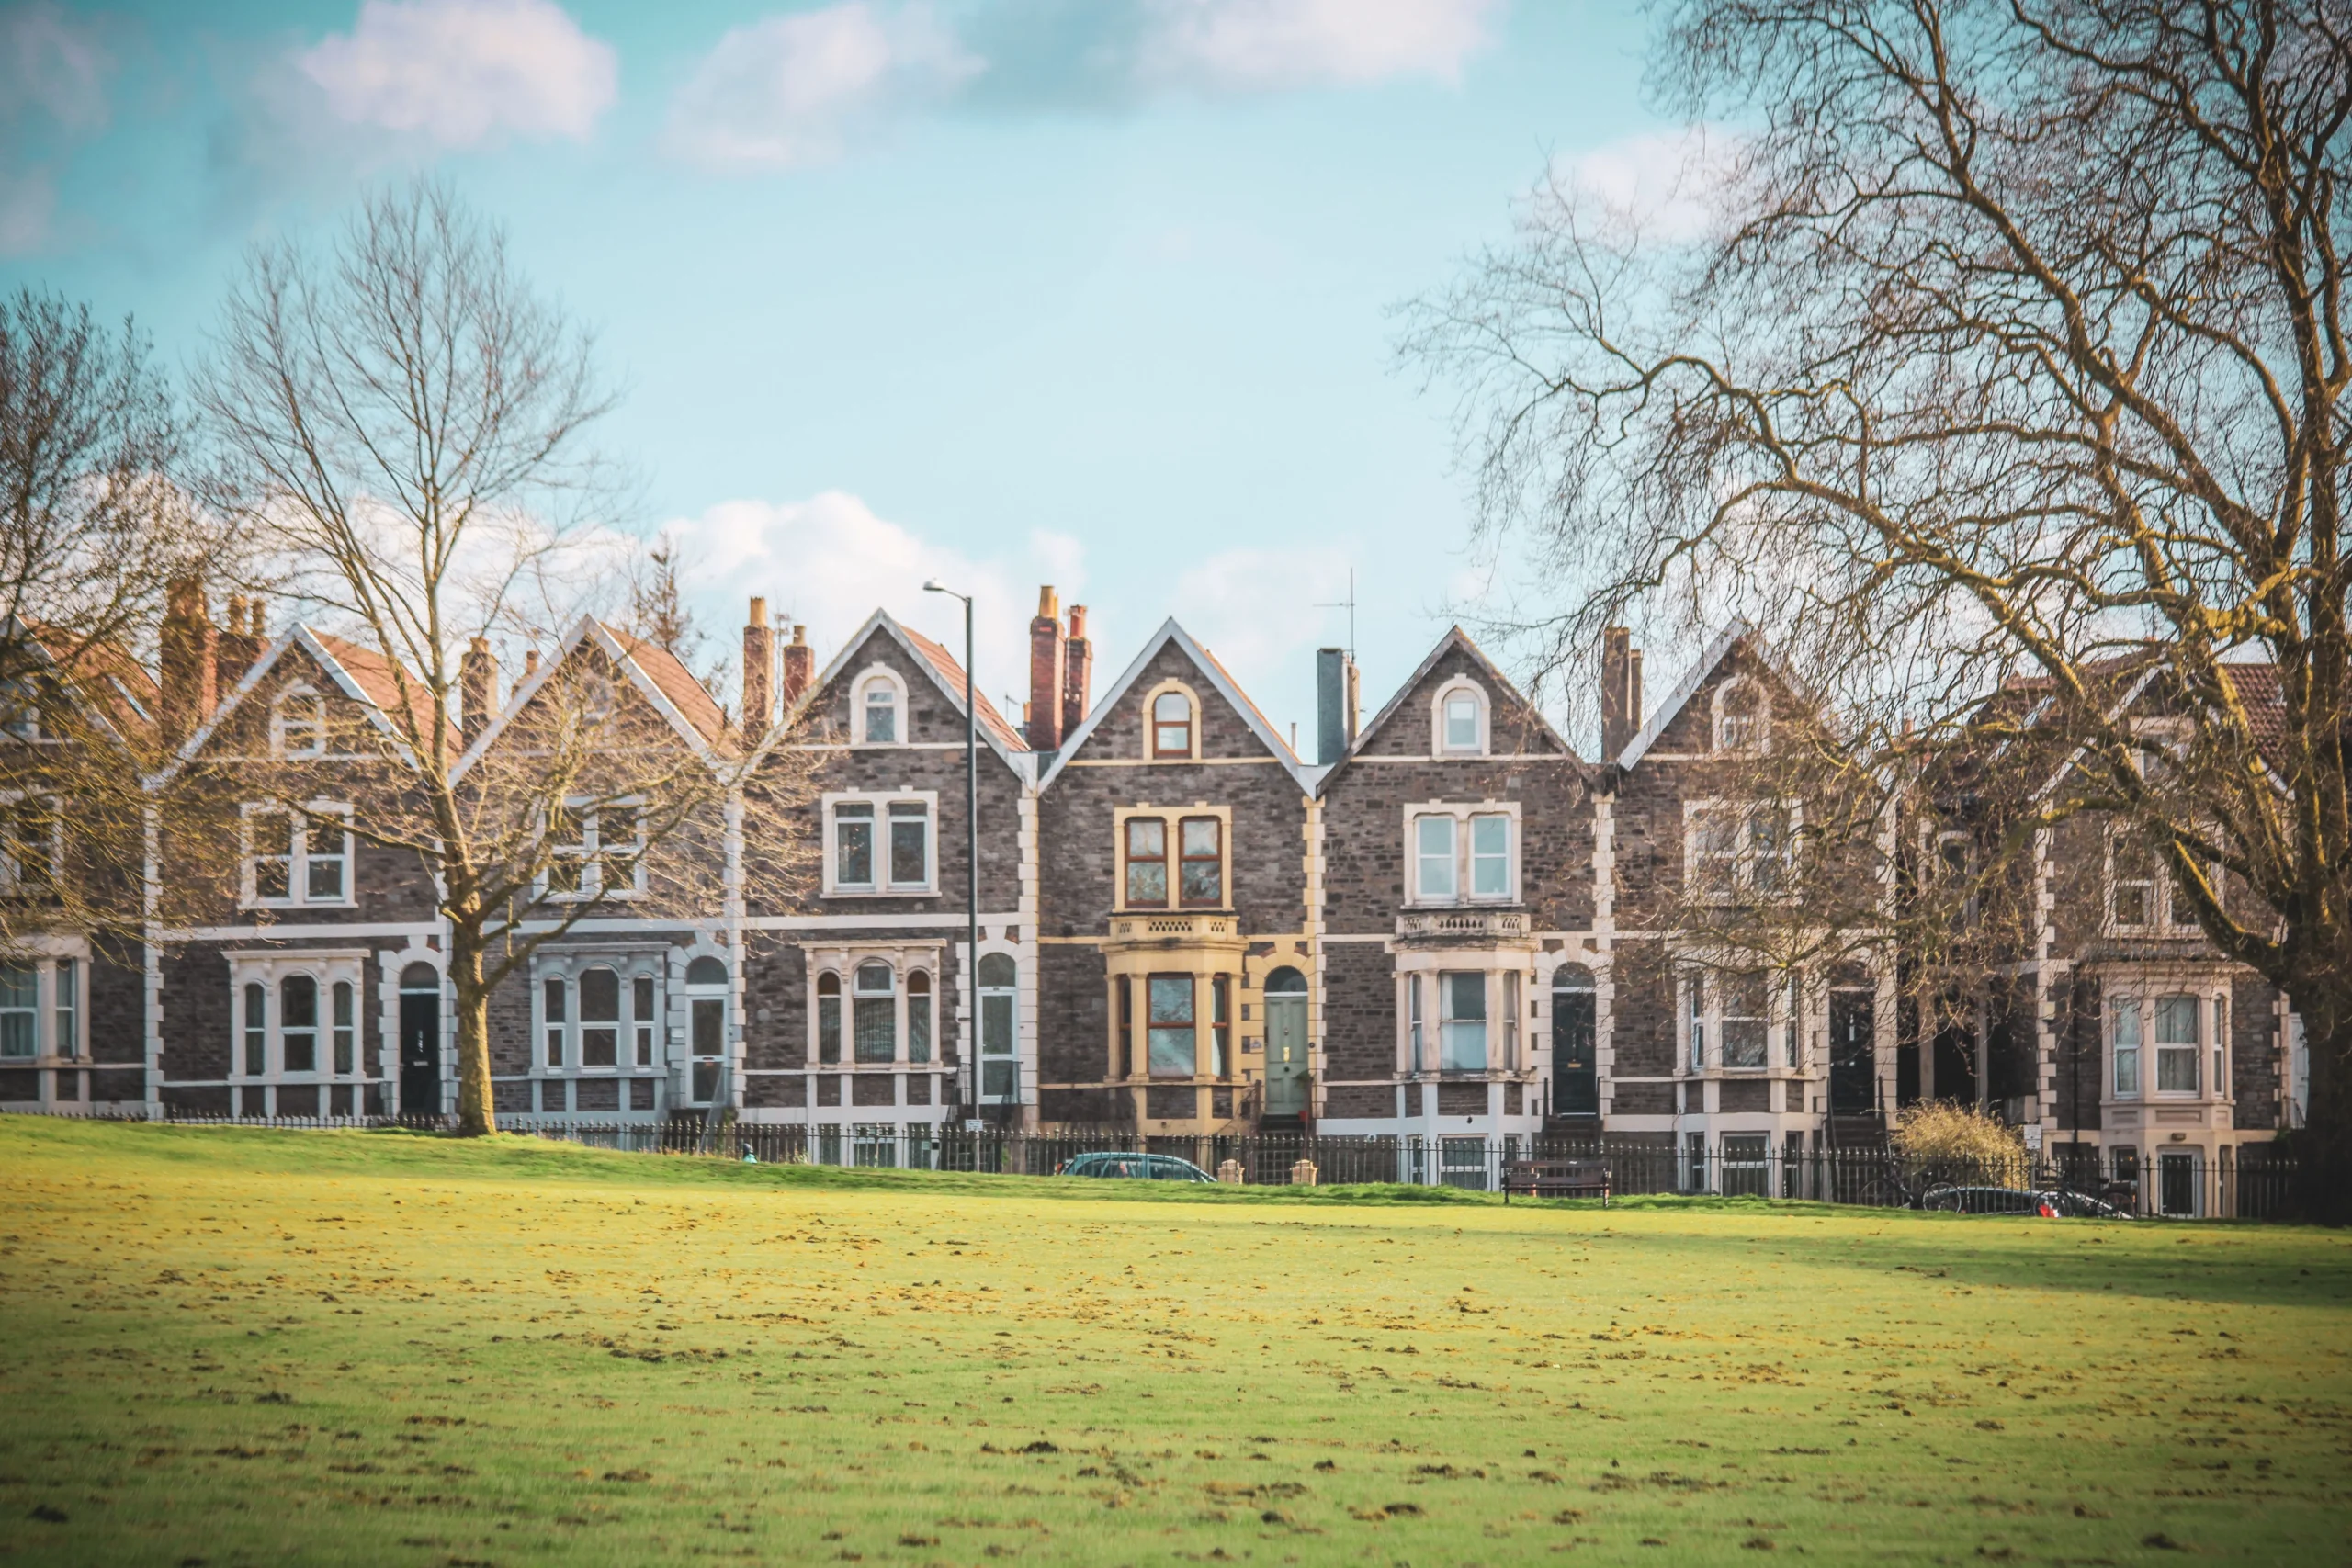
- Property type: Two-bed terraced house
- Condition: Requires cosmetic renovation (kitchen, bathrooms)
- Location: Hazel Grove, Stockport
- Post-renovation value estimate: £225,000
Step 1: Acquisition Costs (Week 1-2)
- Hammer price: £185,000
- Buyers premium (4%): £7,400
- Auction finance arrangement: £1,850 (1%)
- Legal fees: £750
- Valuation: £500
Total acquisition costs: £196,500
Step 2: Bridging Finance Arrangements
- Bridging loan: £185,000 (100% of hammer price)
- Loan-to-value: 100%
- Interest rate: 1% monthly (12% annually)
- Expected term: 8 months
Monthly interest cost: £1,850
Step 3: Renovation (Month 1-4)
- Renovation budget: £25,000
- New kitchen: £8,000
- Bathrooms (2): £12,000
- Flooring and decoration: £5,000
Post-renovation value: £225,000
Step 4: Tenant Arrangement (Month 4-5)
- Property let at £750 monthly
- 6-month AST established
- Mortgage affordability now demonstrable
Step 5: Refinance to Buy-to-Let Mortgage (Month 6-8)
- Buy-to-let mortgage value: £225,000
- LTV: 75% (£168,750 mortgage)
- Rate: 5.2% fixed 5-year
- Monthly mortgage: £1,623
- Bridging repaid from mortgage advance
Financial Outcome
Investment summary:
- Initial outlay: £56,500 (deposit + costs + renovation)
- Property value: £225,000
- Mortgage owed: £168,750
- Equity built: £56,250
- Monthly rental income: £750
- Rental coverage: 146% (covers mortgage plus costs)
Key Takeaways
- Auction strategy works: Initial value increase from renovation supports buy-to-let
refinance - Bridging bridges the gap: Allows rapid acquisition, renovation and tenant establishment
- Refinancing saves money: Move from 12% bridging to 5.2% mortgage
- Strategy works if planned properly: Timeline, costs and exit clearly mapped